Amas · provisional setup from posts/catalogue: ORB 1:1
Template coded in system: No
No Amas template. Generic smt-python/templates/orb_basic.yaml (09:30–09:45 range, first close beyond before 11:00, stop opposite side, 1R) is close in shape but not his rule (he targets the opposite extreme after one side forms first).
Template pending: no video transcripts yet
Source notes so far (draft, not a template, not used as an A+ gate)
Two @AmasPFT X posts (amas_orb_1to1_2026-10-01.png, amas_orb_short_mirror_2026-10-01.png) + payout post; STRATEGY_NOTES.md.
01. Instrument & data
Enable ........................... True
Instrument ...................... NQ (chart shown) [X amas_orb_1to1_2026-10-01.png]
ChartTimeframe .................. 1m chart shown; execution TF not stated [X amas_orb_1to1_2026-10-01.png]02. Sessions
Enable ........................... True
TimeZone ........................ America/New_York
ORBStart ........................ 09:30 [X amas_orb_1to1_2026-10-01.png]
ORBEnd .......................... 09:45 (first 15m candle) [X amas_orb_1to1_2026-10-01.png]03. Bias
Enable ........................... not stated
BiasMethod ...................... not stated04. Setup
Enable ........................... True
LongCondition ................... ORB low forms first → target the ORB high [X amas_orb_1to1_2026-10-01.png]
ShortCondition .................. ORB high forms first → target the ORB low [X amas_orb_short_mirror_2026-10-01.png]
AggressiveFlowFilter ............ "Aggressive buying/selling" named, undefined [X amas_orb_1to1_2026-10-01.png]05. Entry
Enable ........................... not stated
EntryTrigger .................... not stated06. Stop loss
Enable ........................... not stated
StopMode ........................ not stated (only the 1:1 RR framing)[X amas_orb_1to1_2026-10-01.png]07. Take profit
Enable ........................... True
TargetMode ...................... Opposite ORB extreme [X amas_orb_1to1_2026-10-01.png; amas_orb_short_mirror_2026-10-01.png]
RiskReward ...................... 1:1 [X amas_orb_1to1_2026-10-01.png; payout post]08. Risk & limits
Enable ........................... True
MaxTradesPerDay ................. 1 [X payout post (amas_tradeify_live_payout_2026-05-11.png)]
RiskPerTrade .................... not stated09. Filters
Enable ........................... not stated
NewsFilter ...................... not stated
Opening range = 09:30–09:45 ET first 15m candle · X amas_orb_1to1_2026-10-01.png
Note which ORB extreme formed first (low first → long, high first → short) · X amas_orb_1to1_2026-10-01.png; amas_orb_short_mirror_2026-10-01.png
Aggressive buying (long) / selling (short) seen; he does not define it · X amas_orb_1to1_2026-10-01.png
Target the opposite ORB extreme · X amas_orb_1to1_2026-10-01.png
1:1 risk-reward · X amas_orb_1to1_2026-10-01.png
One trade a day · X amas_tradeify_live_payout_2026-05-11.png
Testing rules
Tuning 1 Jan – 30 Apr · four months testOut-of-sample 1 May – 31 Jul · three months testHoldout 1 Aug – 14 Sep · about six weeks testCommission $5 round turn, NQ
01
Lock the rules before testing
Every rule is written in full as a parameter list (sessions, setup conditions, entry, stop, target, max trades, bias) with a version number and a date before any data is run. Nothing changes once testing starts. Any change is a new version, and that version starts again at rule 1.
Name the instrument and the data file. Times are New York time, prices are rounded to the tick, and contract roll weeks are removed. The same cleaned data is used in every window.
This is the only window where settings can be adjusted. Rank settings by net profit after commission. Anything with fewer than 100 trades doesn't qualify. Keep the top 20 and lock them.
Out-of-sample: 1 May to 31 Jul (three months test)
Run the locked settings once, exactly as they are. No changes after seeing the results. A setting passes if it makes a net profit and has a profit factor above 1.
A trade only counts if it passes the trader's written A-plus checklist at entry: right session, liquidity swept, bias agrees, entry model confirmed, and stop and target where the checklist says. Failures are logged as B or C trades and kept out of the results.
Every known real A-plus trade from the trader's videos or posts is traced through the A-plus definition, each filter (session, bias, sweep, timeframe, news, caps), the Roman/ZZ entry path (trigger, confirmation, order type, expiry) and the fill. Record the exact step where each one dies. Misses are fixed in the next version, never the current one.
Every result shows, in order: test number, instrument, length in words, average trade, profit factor, win rate, equity curve; then average signed ticks, trade count and drawdown.
Windows run in order, with no extra out-of-sample passes and no retuning after a peek. Under 100 trades or under about three months is a diagnostic, not a pass.
HISTORICAL CROSS-REFERENCENOT this trader's performanceDOES NOT PASS robustness / qualificationMGC 1m onlycap 50 contractsfee_rt $1.98+63 TEST
Not this page's trader. Same Lanto micro-gold pack is shown on every playbook page as a Lanto historical cross-reference only. It is not a result for the trader named on this page, not a multi-timeframe top-20 board, and not a fresh qualification.
DOES NOT PASS robustness / qualification. Ex-top-5 net is negative in IS, OOS and HO for both cells below. Placebo median nets are also negative in every period. Treat as historical research context only — do not promote, do not trade from this, do not read as a locked playbook winner.
Source. PC6 Lanto run artifacts (lab s1_lab63, grid S1-grid v0.3-capped50, +63 TEST). Rank export generated_at_local 2026-11-05 20:13:57 (AEST). Pack built 2026-11-07. Instrument MGC, timeframe 1m only in that export. Overrides: u_golden_zone=Gate, u_max_contracts=50.
Scripts caveat. Bundled plugin/tests are v81 / box REFERENCE copies (h7_pkg_deploy_v81 paths), not proven bit-identical to the PC6 run that produced these RESULTS. RESULTS record h7_version7.0.0-dev.3.1.1…. Exact equity-rank exporter and dedicated cell launch scripts are MISSING (not invented).
Costs (verified from trades CSV + RESULTS). Round-turn fee $1.98 per contract (fee/qty = 1.98 on all 94 trades; fee_source cites NinjaTrader Lifetime all-in $0.99/side, table fees_verified_20261030.csv). Slippage is per-trade from the CSV (most trades ≈ $2/contract; some rows 1.0–1.57 — model beyond the CSV is unknown). risk_mult takes values 0.5 or 1.0 only in the CSV; further risk policy is unknown. Contract cap 50.
Trade span (CSV opened_at). 2025-06-20 through 2026-10-05 (America/New_York offsets on stamps). Exact IS/OOS/HO calendar cut dates are not stated in RESULTS beyond chunk labels IS vs OOSHO — unknown stays unknown.
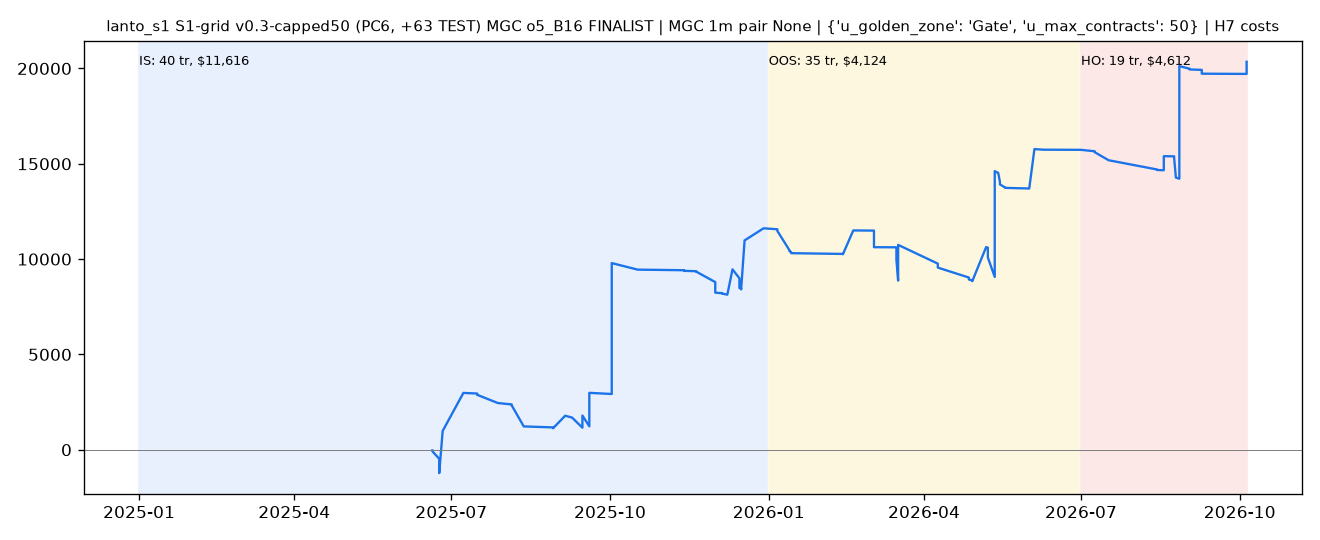
HISTORICALex-top5 FAIL all periods94 tradestag o5_B16
Tag lanto_s1_S1-grid_v0.3-capped50_PC6_MGC_o5_B16 · label FINALIST in source export (name only — does not pass ex-top5 robustness).
Net (all periods)
+$20,351.38
Trades
94
Fee RT / contract
$1.98
Max contracts
50
IS
40 tr · net +$11,615.70 · PF 2.65 · max DD $1,852.98 · ex-top5 −$3,783.42 · placebo median −$1,869.30
OOS
35 tr · net +$4,123.84 · PF 1.49 · max DD $2,769.64 · ex-top5 −$8,404.26 · placebo median −$1,203.66
HO
19 tr · net +$4,611.84 · PF 2.73 · max DD $1,521.20 · ex-top5 −$2,651.08 · placebo median −$600.66 · source marks HO_thin
Curve checked: CSV net sum +$20,351.38 matches RESULTS period sum and the equity PNG below.
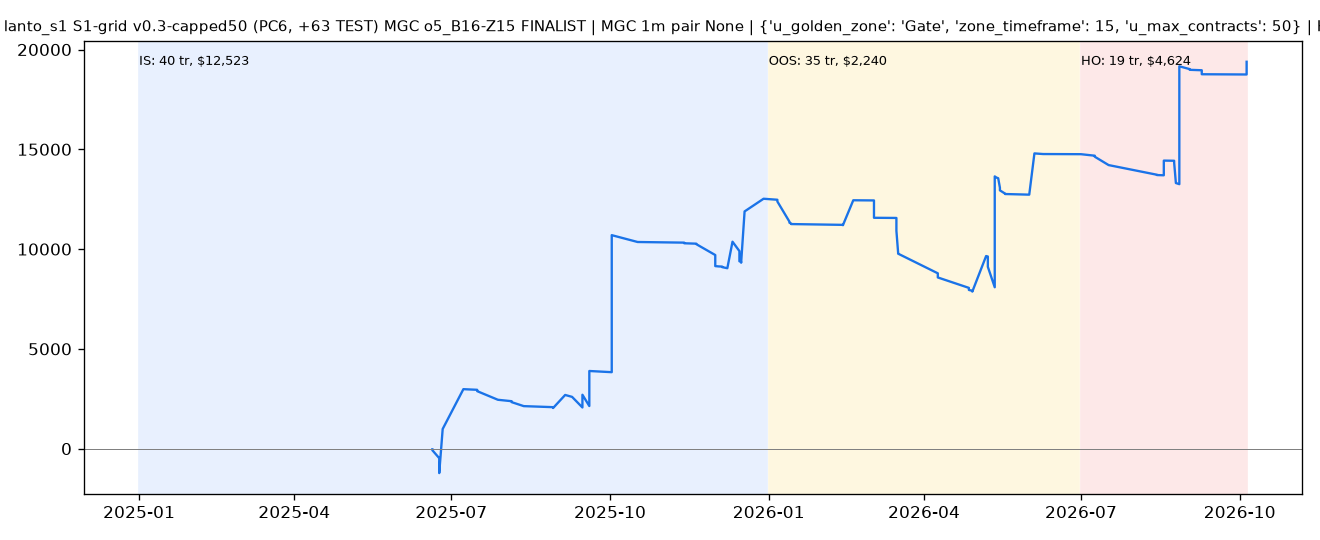
B16-Z15 companion · MGC 1m · cap 50 · net +$19,387.34
HISTORICALex-top5 FAIL all periods94 tradestag o5_B16-Z15
Tag lanto_s1_S1-grid_v0.3-capped50_PC6_MGC_o5_B16-Z15.
Net (all periods)
+$19,387.34
Trades
94
Fee RT / contract
$1.98
Max contracts
50
IS
40 tr · net +$12,523.16 · PF 3.04 · max DD $1,656.58 · ex-top5 −$2,875.96 · placebo median −$1,999.34
OOS
35 tr · net +$2,240.40 · PF 1.27 · max DD $4,653.02 · ex-top5 −$8,404.32 · placebo median −$898.60
HO
19 tr · net +$4,623.78 · PF 2.74 · max DD $1,509.26 · ex-top5 −$2,639.14 · placebo median −$666.22
Curve checked: CSV net sum +$19,387.34 matches RESULTS period sum and the equity PNG below.
Not a top-20 board. This section posts two verified 1m cells only. No multi-TF top-20, no padded ranks, no invented entry-style leaderboard. Per David’s Stage 1–3 plan, each playbook still needs its own top-20-per-timeframe board from that trader’s tests — separate work, not this pack.
Posted by Dashboard · DASHBOARD DEV · prepared 7 Nov 2026 · remote publish awaits separate authorize (serialize after testing-plan buttons).